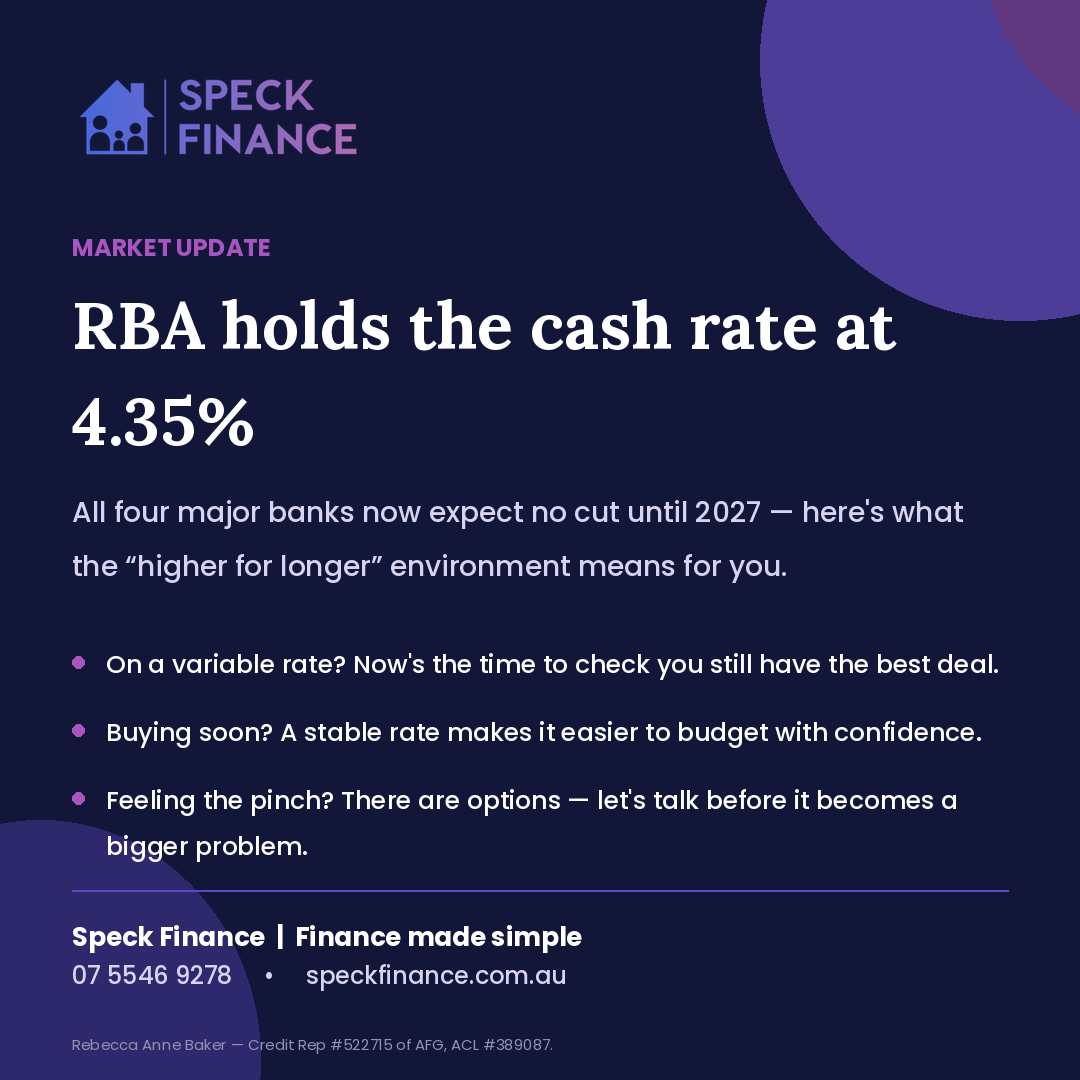
This article preserves a previous SPECK Finance social update about an RBA cash-rate decision. Cash rates, lender pricing and forecasts can change, so the figures shown in the original graphic should not be treated as current.
A cash-rate hold does not mean every loan remains competitive
Even when the RBA leaves the cash rate unchanged, lenders may price products differently. Existing-customer rates, new-customer offers, discounts, fees and loan features can all vary.
What a home-loan review considers
- Your current interest rate, repayments and remaining loan term
- Fixed or variable rate arrangements and relevant expiry dates
- Offset, redraw and other features you actually use
- Available equity and lender valuation
- Refinance costs and the longer-term impact of resetting the loan term
Planning to buy?
Interest rates are only one part of the assessment. Borrowing capacity also depends on income, living expenses, existing debts, dependants, credit limits and lender policy.
For current cash-rate information, always refer to the Reserve Bank of Australia. SPECK Finance can help explain how current lender options may apply to your individual circumstances.